dayileyvasSeptember 24, 20264 Mins read27
Spot Market Rates Mixed as Diesel Costs Keep Climbing
The Spot Market delivered mixed results in the latest week as freight activity rebounded from the Labor Day slowdown. Flatbed rates climbed sharply, while dry van and refrigerated rates moved lower.
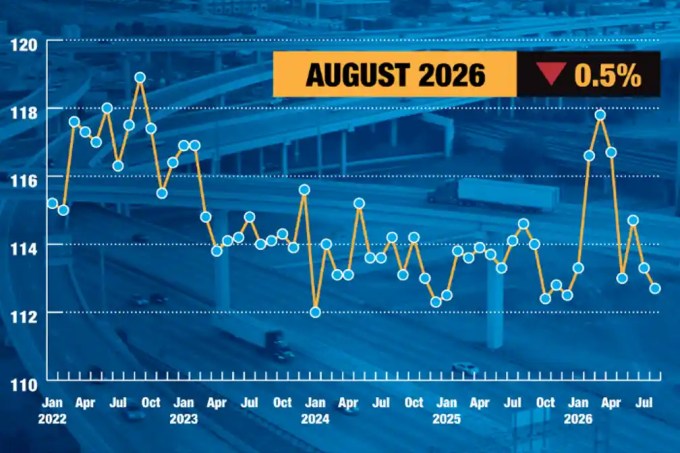
Total load activity increased 26.7% during the week ending Sept. 18, according to the latest Truckstop.com Spot Market Insights report from FTR. Volume reached its highest level in nine weeks and was about 10% above the same week in 2025.
However, another issue is putting pressure on trucking operations: diesel prices.
The national average diesel price climbed above $6.50 per gallon during the following week. Higher fuel costs mean that some of the recent increase in spot rates is being absorbed by higher operating expenses.
Spot Market Loads Rebound After Labor Day
Total Spot Market load activity reached 161.0, up 26.7% from the holiday-shortened previous week.
Truck postings also increased 13.3% after declining for three consecutive weeks. The Market Demand Index, which measures the ratio of loads to trucks, rose to its highest level in three weeks.
The total broker-posted spot rate increased 2 cents to $3.23 per mile. The gain was driven by flatbed because both major van segments recorded lower rates.
Compared with the same week last year, the total rate was about 41% higher.
However, the year-over-year comparison changes when fuel is considered. Rates excluding FTR’s calculated fuel surcharge were about 35% higher than a year earlier.
Spot-market carriers typically do not receive separate fuel surcharges. FTR uses the calculation as a way to estimate the portion of the all-in rate needed to recover fuel expenses.
Diesel Prices Put Pressure on Spot Market Gains
The fuel situation has become increasingly important when looking at current Spot Market rates.
FTR’s latest calculations were based on the EIA’s weekly national diesel average of $6.285 per gallon for Sept. 14. That was already a record weekly average.
Since then, diesel has climbed even higher.
The U.S. Energy Information Administration reported an average on-highway diesel price of $6.529 per gallon for Sept. 21. That was an increase of 24.4 cents in one week.
Diesel was also $2.78 per gallon higher than a year earlier.
The increases have been especially sharp in some regions. Midwest diesel reached $6.680 per gallon for Sept. 21, up 43 cents in one week. West Coast diesel averaged $7.456, while California reached $8.246 per gallon.
EIA says elevated crude oil prices and tight global supplies of distillate fuel have helped drive diesel higher. Refining margins also have contributed to the increase.
For trucking operations, higher fuel prices can quickly consume a larger share of revenue. This is especially important in the Spot Market, where carriers generally negotiate an all-in rate rather than receiving a separate fuel surcharge.
Dry Van Rates Fall Despite Stronger Load Volume
Dry van spot rates declined by just under 3 cents to $2.74 per mile.
Despite the weekly decrease, rates remained close to 45% higher than during the same week in 2025.
Regional results were mixed. Rates increased sharply on the West Coast and posted a smaller gain in the Mountain Central region. All other regions recorded decreases.
Freight volume showed a much stronger weekly result.
Dry van loads jumped 27.8% following the Labor Day week. Volume was 28.5% higher than during the same week last year, with load postings increasing in every region.
Seasonal patterns could bring additional pressure to rates. FTR noted that dry van spot rates almost always decline during week 38.
Refrigerated Spot Market Rates Drop 6.4 Cents
Refrigerated rates fell 6.4 cents to $3.56 per mile. It was the segment’s first weekly rate decline in five weeks.
Even with the decrease, reefer rates were about 49% higher than during the same week last year. FTR said that was the strongest year-over-year comparison in 15 weeks.
Rates increased in the West Central, South Central and West Coast regions. However, they fell sharply in the Midwest and Southeast and also declined in the Northeast.
Refrigerated load activity increased 14% for the week. Volume was nearly 38% higher than the comparable 2025 period.
Load postings increased across all regions, although growth was notably weaker in the South Central region.
Flatbed Rates Record Unusual Weekly Increase
Flatbed produced the strongest rate movement in the latest Spot Market results.
Rates increased more than 5 cents to $3.31 per mile. FTR said the increase was the largest for a comparable week in data going back to at least 2008.
Flatbed rates were approximately 42% higher than during the same week in 2025.
Every region recorded a weekly increase. The West Coast led the gains, with rates rising 9.6 cents.
Flatbed load activity also rebounded sharply. Loads increased 29.9%, reaching their highest level in eight weeks.
Load postings increased sharply across all regions, although total flatbed volume remained about 1% below the same period last year.
Higher Rates Do Not Tell the Whole Story
The latest Spot Market numbers show a freight market with stronger load activity following the holiday week but different rate trends across equipment types.
Flatbed stood out with gains in both rates and volume. Dry van and refrigerated loads also increased, but their rates moved lower.
Fuel costs add another layer to the results.
The total spot rate is substantially higher than it was a year ago, but diesel is also dramatically more expensive. With the EIA national average now at $6.529 per gallon, the difference between the all-in rate and the fuel-adjusted rate has become increasingly important when evaluating current Spot Market conditions.
The next weekly results will show whether flatbed can maintain its unusual rate strength and how dry van and refrigerated rates perform during a week when seasonal patterns typically favor additional declines.