dayileyvasOctober 26, 20263 Mins read18
Spot Market Rates Slip as Freight Demand Weakens
The trucking spot market remained seasonally sluggish during the week ending October 23, with total load activity and broker-posted rates moving lower. Data from FTR Transportation Intelligence and Truckstop showed that total spot rates fell 2.3 cents per mile. Dry van rates increased modestly, but declines in refrigerated and flatbed rates pulled the overall market lower.
The latest results do not point to a broad freight-market collapse. However, the combination of fewer loads, more available trucks and weaker fuel-adjusted rates indicates that carriers continue to face competitive market conditions.
Spot Market Load Activity Falls Again
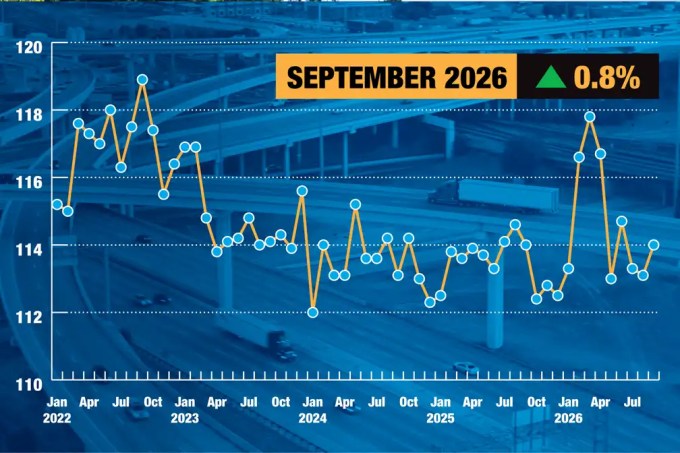
Total spot load activity decreased 2.3% from the previous week, following a decline of more than 1% one week earlier. The Truckstop system recorded a total load index of 140.8.
Load activity remained approximately 7% higher than during the comparable week in 2025. That year-over-year increase suggests the market is moving more freight than it was a year ago, but the weekly numbers show that current demand remains soft.
Truck postings increased 1.6%, meaning more capacity was competing for fewer posted loads. As a result, the Market Demand Index—the ratio of loads to available trucks—fell to its lowest level since January.
For owner-operators and small carriers, that change may translate into more competition for loads and less negotiating leverage on some lanes.
Total Rates Decline to $3.24
The total broker-posted spot rate averaged $3.24 per mile, down 2.3 cents from the previous week. It was the largest weekly decrease in three weeks, although FTR described the change as relatively small for this time of year.
The total rate remained nearly 41% above the same week in 2025. However, fuel costs account for part of that comparison.
FTR also calculated the rate after removing an estimated fuel-surcharge component. On that basis, rates declined 3.7 cents for the week and were slightly more than 33% above the previous year.
That difference matters because spot-market carriers do not always receive a separate fuel surcharge. Higher all-in rates can appear favorable while a larger share of the payment is needed to cover diesel.
Dry Van Rates Rise Despite Fewer Loads
Dry van was the only major equipment category to record a weekly rate increase.
Broker-posted dry van rates rose 2 cents to $2.87 per mile. That was slightly stronger than the typical seasonal movement for this week and more than 48% above the comparable 2025 rate.
Regional results were mixed. Rates declined for loads originating in the South Central and Southeast regions. They increased elsewhere, with the strongest improvement reported on the West Coast.
Dry van load activity decreased 1.6%. Even with that decline, volume remained 22.5% above the same week last year.
West Coast load postings increased, while every other region recorded a decline. Changes in the Midwest and Mountain Central regions were minimal.
The combination of lower volume and slightly higher rates suggests that lane-specific capacity conditions helped support pricing. It does not indicate that dry van demand strengthened across the entire country.
Refrigerated Rates and Loads Move Lower
The refrigerated segment recorded the weakest weekly rate movement.
Reefer spot rates fell 5.5 cents to $3.49 per mile after declining 1.5 cents during the previous week. The latest decrease was weaker than normal seasonal performance because refrigerated rates had increased during the comparable week in each of the previous four years.
Rates were still nearly 42% higher than during the same week in 2025.
South Central reefer lanes recorded particularly sharp rate declines. Rates also fell in most other regions. The West Coast posted an increase, while the Southeast was nearly unchanged.
Refrigerated load activity decreased 5.4%, reversing the previous week’s 3% gain. Volume was more than 5% below the comparable 2025 week, making reefer the only principal equipment category with a meaningful year-over-year load decline.
Load postings increased sharply on the West Coast but fell in every other region.
Flatbed Market Continues Seasonal Decline
Flatbed rates decreased 1.7 cents to $3.32 per mile. The decline followed a nearly unchanged result during the previous week and was broadly consistent with normal seasonal movement.
Rates remained 42% higher than during the same week last year.
Regional pricing varied. Flatbed rates increased in the Midwest, West Coast and Northeast but declined in the remaining regions.
Flatbed load activity fell 3.9%, approximately matching the previous week’s decline. Volume was unchanged from the comparable week in 2025.
Load postings increased on the West Coast and in the South Central region but decreased elsewhere.
What the Latest Results Mean for Drivers
Rates remain substantially higher than a year ago, particularly for dry van freight. However, diesel expenses explain part of those gains, and the fuel-adjusted comparison is less favorable than the all-in rate suggests.
The declining Market Demand Index is another cautionary signal. With fewer posted loads and more available trucks, carriers may encounter greater competition and weaker negotiating power outside stronger regional markets.
Dry van pricing provided the week’s clearest positive result. Reefer conditions weakened more noticeably, while flatbed continued a largely seasonal decline.
The results suggest that freight selection, deadhead distance, fuel consumption and regional positioning remain as important as the advertised rate per mile. A higher gross rate does not necessarily produce stronger operating margins when fuel and repositioning costs are included.